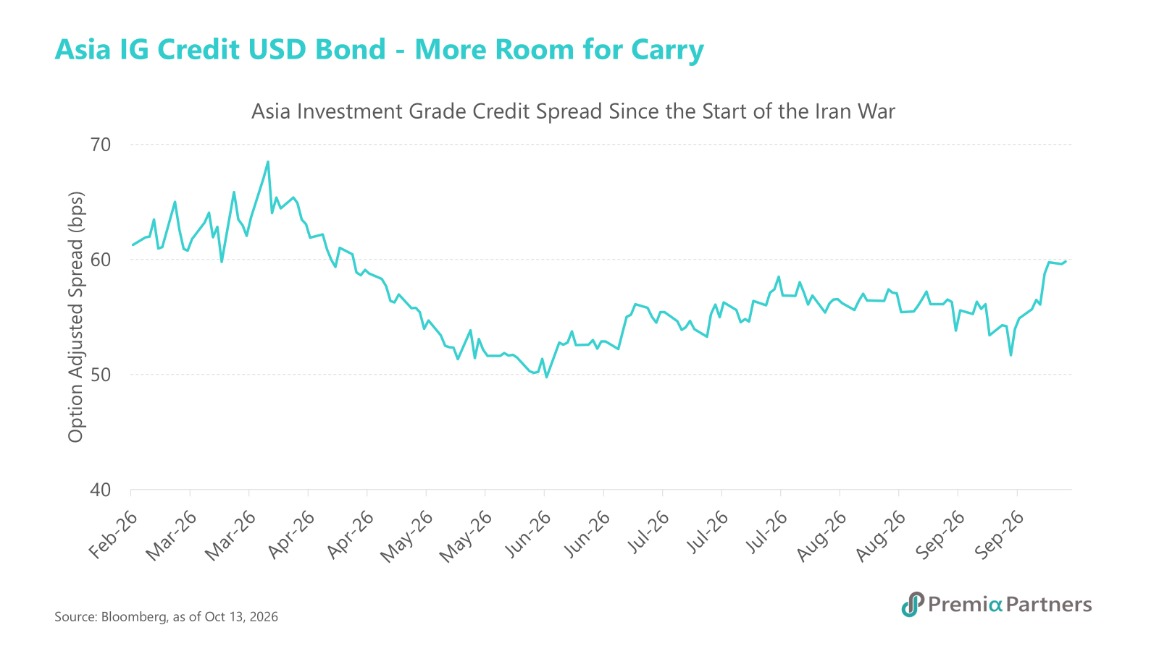
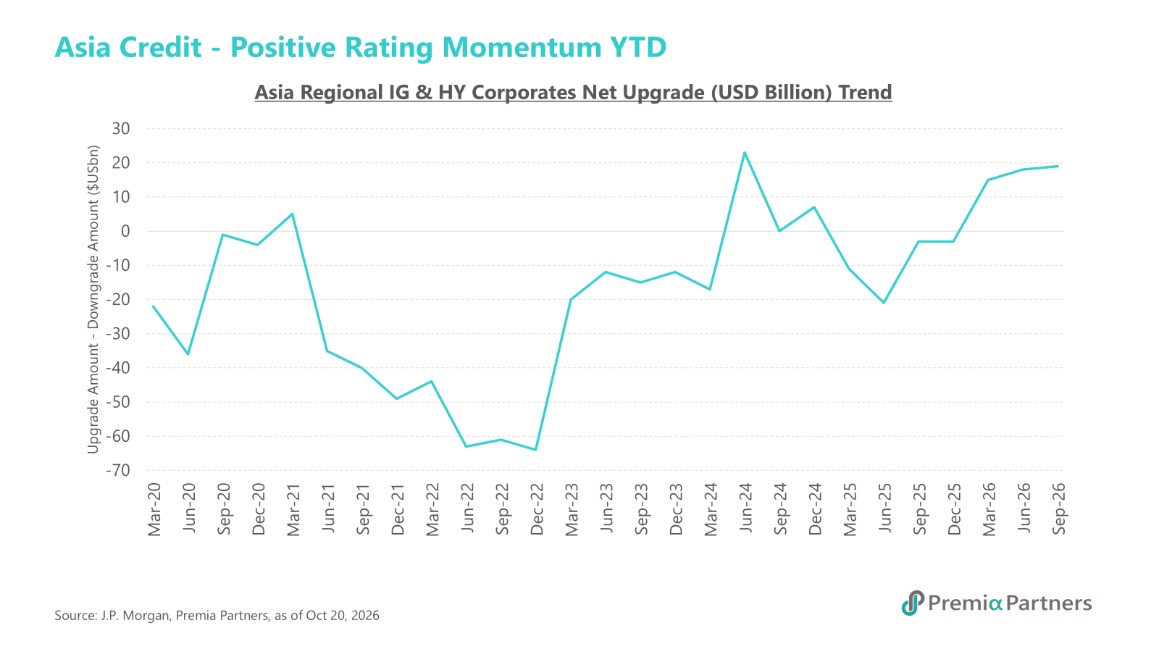
J.P. Morgan data show net rating upgrades for Asian investment grade (IG) and high yield (HY) corporates (by debt amount) turning positive from March, reaching roughly US$19bn by September 2026. The improvement reflects firm corporate fundamentals: steady earnings growth, resilient macro conditions, limited default activity and disciplined primary supply. Meanwhile notwithstanding the equity shock triggered by MSCI consultation for potential reclassification of Indonesia from emerging markets to standalone status, reaction to its bond market has been much calmer with yields recovering soon after initial selloff.
For Asian bond allocators, the next test of this trend would be the market receptiveness to step-up in borrowing by China's IG technology leaders amid concerns for massive AI debts in the US. Tencent raised about US$5.7bn last week across US$1.8bn of dollar notes and RMB26bn (US$3.9bn) of offshore yuan bonds, with the 10-year dim sum tranche priced at 2.40% against over 6% on the dollar notes. It was its second offshore deal this year after a US$4.7bn transaction in June, with proceeds reportedly directed largely at AI-related capex. Rating agencies have yet to react, but bond investors already have: despite global unease over AI monetisation and a semiconductor selloff, order books topped US$23bn, more than four times the deal size.
Large debt raises would normally add leverage and weigh on ratings, but three factors suggest the risk is contained. Tencent's deals sit comfortably within its balance-sheet capacity even with capex expected to exceed RMB200bn (US$30bn) a year through 2027. Chinese big tech is also tapping equity and cheap offshore RMB rather than dollar debt alone and in a much more moderate scale compared to global peers: Alibaba raised HK$80bn (US$10.2bn) through a Hong Kong share placement in August, and the coupon gap Tencent secured has Meituan now considering a dim sum sale of its own.
As for Premia J.P. Morgan Asia Credit Investment Grade USD Bond ETF (3411 HK) which covers a diversified basket of IG issues, the exposure is small relative to the asset class: in the corporates make up around 56% of the ETF but TMT less than 7%, leaving holders exposed to the broader upgrade corporate credit upgrade cycle with limited exposure to Chinese big tech issuance.